
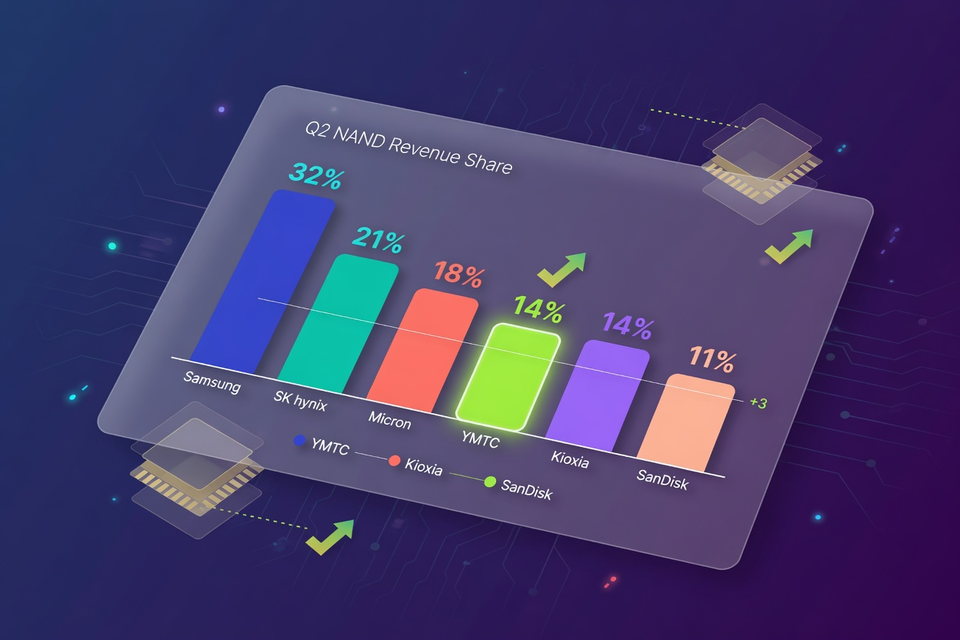
Counterpoint Research has posted its second-quarter NAND revenue share table with YMTC at 14%, level with Kioxia and three points above SanDisk, after the firm's own August 12 release ranked the Chinese supplier fifth in revenue behind Micron and Kioxia.
The table gives Samsung 28%, SK Hynix 19%, Micron 15%, Kioxia 14%, YMTC 14% and SanDisk 11% for the quarter. The note beneath it does not pretend the YMTC line was in the plan: "YMTC earned more revenue than we had expected. Its market share in the second quarter was 14%."
Decoded: the whole argument of the August 12 release was that bits and dollars had come apart. That release put YMTC third in shipments at 14%, ahead of Kioxia and Micron, and then explained why that did not show in the money: "Shipment volume, however, does not translate directly into revenue. YMTC ranked third in shipments this quarter but closed fifth in terms of revenue, behind Micron and Kioxia, because its product mix is still concentrated in consumer applications with a low share of high-priced data-center eSSDs." On the revenue table, fifth belongs to SanDisk, and YMTC's 14% of revenue matches its 14% of shipments. The gap the release was built on has closed on Counterpoint's own numbers, at least at the rounded percentage.
Where the release's revenue ranking went, the table does not say. The August text ranks YMTC behind Micron and Kioxia without mentioning SanDisk at all, so either SanDisk sat outside that count or YMTC's revenue has been revised up, and the firm's own wording, "more revenue than we had expected", points to the second. Neither page reconciles the two, and they cite differently named products: a Q2 2026 Memory & Storage Tracker on the release, a Memory Tracker and Forecast Insights Report for Q2 2026 under the table.
Micron is the mirror image. It shipped the fewest bits of the five suppliers in the release's shipment ranking and books the third-largest revenue on the table, up two points from 13% in the first quarter. Counterpoint's explanation takes three short sentences: "Samsung maintained the first place with a 28% marketshare. SK hynix came second with 19%. And Micron came third, helped by high selling prices." Translated, Micron's flash is going into drives priced at this year's rates, and volume is beside the point.
Elsewhere the table moved a point at a time. Samsung slipped from 29% to 28% quarter on quarter, SK Hynix rose from 18% to 19%, Kioxia held at 14%, and SanDisk lost two points, from 13% to 11%, the largest fall on the sheet. Counterpoint says the NAND market grew 70% in the quarter after 90% growth in the first, with prices up 55% quarter on quarter. The page does not state the base for the 70%, but if both figures are sequential, the implied bit growth is under 10%, my arithmetic, which means nearly all of the quarter's revenue growth came from price.
The release's closing line reads, in hindsight, as a warning to the supplier it had just ranked fifth: "with servers set to take most NAND bits, profitability through 2027 will be decided less by who ships the most bits, but who ships the right mix." YMTC's mix has now produced dollars on a par with Kioxia's, while Kioxia sends more than 30% of its shipments to servers on the release's own figure. That is either a revision Counterpoint owes its readers an explanation for, or evidence that consumer NAND at this year's prices earns more than the release allowed.

Leave a Reply