
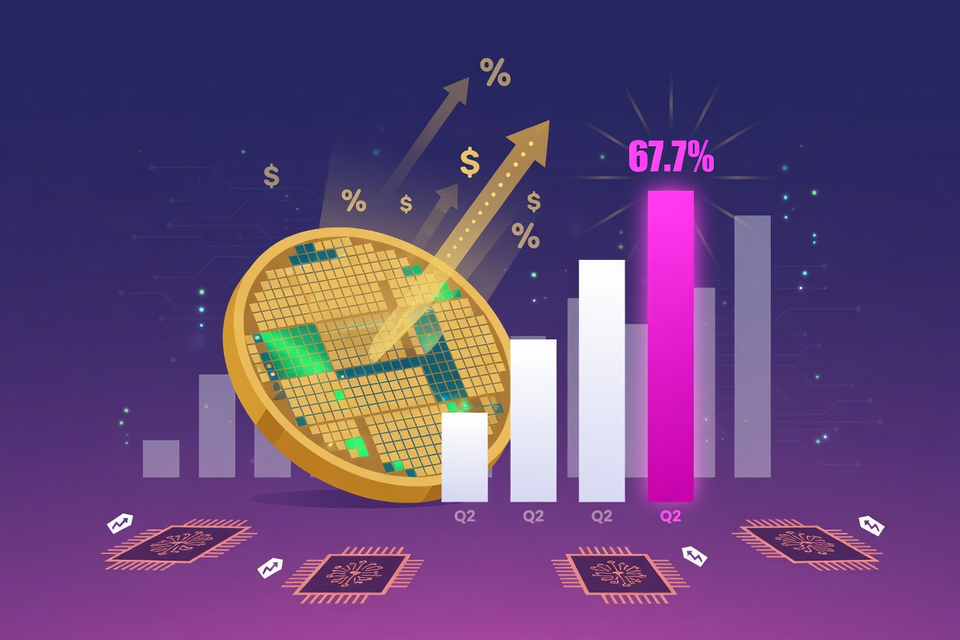
The company that builds nearly every advanced AI chip on the planet has posted the kind of quarter that makes its customers wince and its shareholders beam. TSMC reports second quarter revenue of 40.20 billion US dollars and a gross margin of 67.7 percent, according to the results package on its investor relations site. I have covered foundry earnings for years, and I still read that margin line twice.
A quick refresher over coffee. TSMC is a foundry, which means it manufactures chips that other companies design. Nvidia, AMD and Apple draw the blueprints; TSMC runs the fabs that turn those blueprints into working silicon. Think of it as the world's most exclusive print shop, except there are only a handful of printers on Earth and the ink is measured in atoms.
The numbers, plainly. Revenue of 40.20 billion dollars works out to roughly 1,270 billion New Taiwan dollars at the company's stated exchange rate of 31.60, and operating margin came in at 60.3 percent. In the same quarter last year the company reported 30.07 billion dollars of revenue and a 58.6 percent gross margin, so sales grew by about a third while the margin widened by roughly nine points.
A gross margin of 67.7 percent means that for every dollar customers pay for finished wafers, about 68 cents remain after manufacturing costs. Most contract manufacturers live somewhere in the teens. When a factory keeps two thirds of the ticket price, it is no longer really selling manufacturing. It is selling the fact that nobody else can do the job at this precision, at this volume, on this schedule.
For the third quarter, TSMC guides revenue to between 44.6 and 45.8 billion dollars with gross margin between 65 and 67 percent. Take the midpoint and the company expects to add roughly 12 percent in a single quarter, which is the sort of sequential step most manufacturers only see in their business school case studies.
Here is why the rest of the industry reads these results like a utility bill. Every AI accelerator Nvidia sells and every server processor AMD ships starts life on a TSMC line, so the cost floor of the entire AI buildout runs through Hsinchu. When the foundry's margin widens, the difference lands somewhere downstream: either the chip designers absorb it or the data center builders do. My electrical engineering professor liked to say the fab always gets paid first. He was talking about my lab fees, but the principle scales.
The full results package sits on TSMC's investor site next to a webcast replay for anyone who enjoys margin arithmetic at two in the morning, a small but devoted club in which I hold a lifetime membership. The more useful read is the guidance line. If AI demand were cooling, the print shop would be the first place it showed, and the print shop just raised its own forecast.


Leave a Reply