
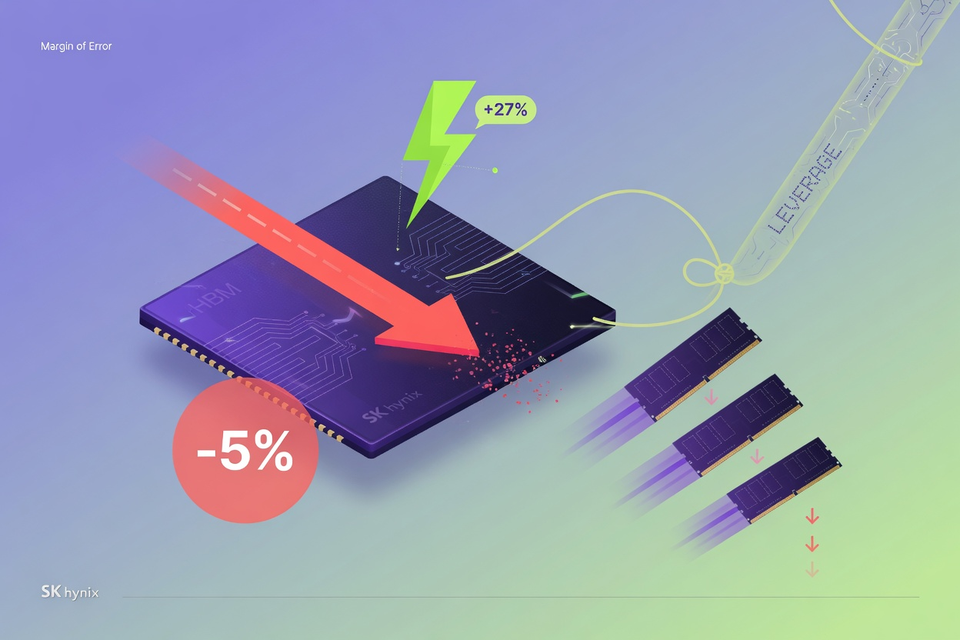
SK hynix gave back 5 percent to $184.50 on Wednesday, one day after its US-listed ADR jumped 27 percent to $193.92, and the rest of the memory complex followed it down without a single piece of bad news to point at.
SanDisk fell 6 percent to $1,658. Western Digital slipped 4 percent to $541, Micron eased 3 percent to $953, and the Roundhill Memory ETF dropped 3 percent to $59. 24/7 Wall St. calls the session "broad profit-taking in the priciest AI beneficiaries" after "one of the strongest rallies in semiconductors this year," and confirms no specific negative catalyst surfaced. Translated, that means nothing changed in DRAM or NAND pricing between Tuesday and Wednesday. What changed is who was holding the shares and how much borrowed exposure they carried.
The year-to-date numbers explain the itch to sell. SanDisk is still up 640 percent this year even after Wednesday's decline, and Micron is up 244 percent. Gains that size convert ordinary Wednesdays into exit opportunities, and the first sign of hesitation becomes its own catalyst.
The more interesting mechanics sit in the SK hynix ADR itself. The listing trades on a thin float, carries a premium to the Seoul-listed shares, and just acquired a set of amplifiers: four daily-reset leveraged single-stock funds launched this week, the Direxion Daily SK Hynix Bull 2X ETF, GraniteShares 2x long and 2x short funds, and a ProShares Ultra product. A 27 percent Tuesday followed by a 5 percent Wednesday is what a thin float looks like when geared products start rebalancing against it. The swing tells us little about how many HBM wafers SK hynix will ship next quarter and a great deal about the trading structure that now surrounds the stock.
For anyone holding the sector on fundamentals, the week's whipsaw reads as noise layered on an unchanged supply story. The memory shortage that produced those year-to-date gains did not loosen on Wednesday. The volatility premium investors now pay to own it, however, has clearly gone up, and that premium is a direct product of the new leverage rather than of anything happening in a fab.
Bootnote: daily-reset leveraged funds rebalance every session, which is why 24/7 Wall St. warns "they can suffer volatility decay, lose money even if SK Hynix rises over periods longer than a day, and lose an investor's full principal in a single session." Volatility decay is arithmetic, not bad luck: a 2x fund tracking a stock that falls 10 percent then rises 11.1 percent ends flat on the underlying and down on the fund. Geared products bolted to a thin-float ADR compound that effect in both directions.


Leave a Reply