
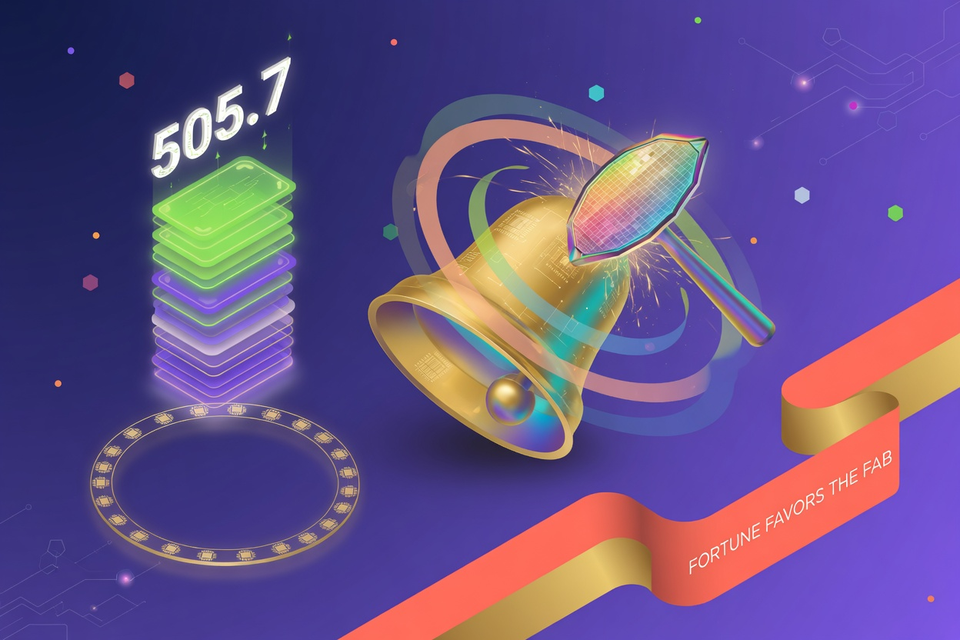
The pure-play foundry model has never had a quarter like it: TSMC closed 2025 with fourth quarter revenue of NT$1,046.09 billion, US$33.73 billion, and net income of NT$505.74 billion, a 48.3 percent net margin, for the quarter ended December 31, 2025.
Growth came from both directions. Revenue rose 20.5 percent year over year in NT dollar terms and 25.5 percent in US dollars, while net income and diluted EPS both climbed 35 percent, according to the company's results release. Gross margin reached 62.3 percent and operating margin 54.0 percent, figures no memory maker sees even at the top of a pricing cycle, and TrendForce reports the profit number is the company's highest ever and the eighth consecutive quarter of growth.
The mix explains the margin. Shipments of 3-nanometer silicon brought in 28 percent of wafer revenue and 5-nanometer another 35 percent, which puts advanced technologies, defined as 7-nanometer and beyond, at 77 percent of the total. That is the AI accelerator complex paying whatever the leading edge costs, and every one of those wafers leaves the fab expecting an HBM stack to be waiting at the packaging line.
"Our business in the fourth quarter was supported by strong demand for our leading-edge process technologies," said Wendell Huang, Senior VP and Chief Financial Officer of TSMC, who then described the next quarter in nearly the same words: "Moving into first quarter 2026, we expect our business to be supported by continued strong demand for our leading-edge process technologies." Read the repetition as the message. Nothing in the order book has changed, the same customers who bought every leading-edge wafer in the December quarter are still buying, and the CFO sees no reason to reach for a second adjective.
Guidance carries the rest of the argument. First quarter revenue is expected between US$34.6 billion and US$35.8 billion, with gross margin of 63 to 65 percent on an assumed exchange rate of 31.6 NT dollars to the US dollar, so the March quarter, traditionally the soft one, would land above the December record at both ends of the range. Management further expects the 2026 capital budget to come in between US$52 billion and US$56 billion.
For the storage and memory trade, a quarter the trade press had spent the preceding days previewing matters less as foundry news than as a demand certificate. DRAM vendors sell HBM against TSMC's accelerator output, and a capital budget of that size is the company saying it expects the build to run through at least another year. The margin structure is the other lesson: 62 cents of gross profit on the dollar goes to the firm that owns the scarce step, a point the memory industry's own packaging investments suggest it has absorbed.
Bootnote. TSMC invented the pure-play foundry business model at its founding in 1987, and the scale it now operates at is easy to underestimate. By its own count the company deployed 305 distinct process technologies and manufactured 12,682 products for 534 customers in 2025. The record quarter belongs to a firm that builds nearly everything for nearly everyone, and charges accordingly.


Leave a Reply