
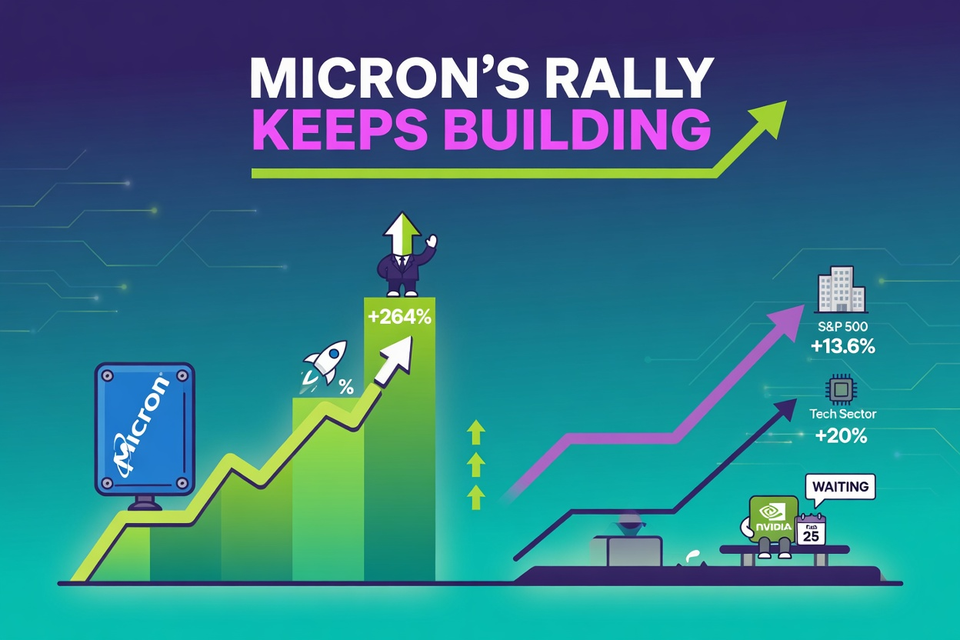
Micron shares have gained 264% over the past 52 weeks, outpacing the S&P 500's 13.6% gain and the Technology Select Sector SPDR Fund's 20% rise over the same stretch, and the memory maker's latest earnings gave analysts little reason to bet against the run continuing.
The company's fiscal first quarter showed adjusted gross margin expanding to 56.8% from 45.7% the prior quarter and 39.5% a year earlier, while adjusted operating margin reached 47%, a jump of 12 percentage points sequentially and 19.5 points from a year ago. Adjusted earnings per share came in at $4.78, up 167% year over year. Wall Street's consensus estimate for full fiscal 2026 now sits at $32.19 a share, implying growth of more than 319%.
Supply has done as much for the stock as earnings. Micron has sold out of high-bandwidth memory chips through 2026 and has told analysts it can meet only about 60% of demand for AI memory this year, a gap that keeps pricing power on its side. The company is the leading supplier of HBM to AI chipmakers including Nvidia and Advanced Micro Devices, and Wall Street has treated every sign of tightening supply as a reason to raise price targets rather than trim them. Stifel raised its target to $360 from $300 on Jan. 20, reaffirming a buy rating and citing AI cloud demand and fab acquisitions as the drivers; the stock rose 6.6% in the session that followed. Of the 40 analysts covering Micron, 31 rate it a strong buy, six a moderate buy, and three a hold, and the shares trade above the average price target of $330.46 even after the run. One analyst has set a target of $500, implying further upside of roughly 48% from the stock's Jan. 15 closing price of $336.63.
By comparison, the past year has been quieter for Nvidia, up 38% in 2025 against the 264% posted by its biggest memory supplier, but its next test carries more weight for the sector. The company reports fourth-quarter fiscal 2026 results on Feb. 25, with the 40 analysts tracking the stock expecting earnings per share of $1.52, a 71% increase from the same quarter last year, on revenue of $65.47 billion, up nearly 66.5%. Nvidia's gross margin ran around 73.4% last quarter, and any move in that number, along with commentary on its Blackwell chip backlog and the newer Vera Rubin platform, is likely to matter more to investors than the headline earnings beat Nvidia rarely misses. Unverified media reports that China may be blocking renewed sales of Nvidia chips there add a variable analysts cannot yet size.
Both stocks are now priced for continued acceleration rather than ordinary growth. Micron trades at roughly 12 times forward earnings despite its rally, a valuation that assumes the earnings estimates keep climbing. Nvidia, at close to 40 times forward earnings, is pricing in a bigger margin for error. The memory shortage lifting Micron is also the mechanism most likely to eventually squeeze Nvidia's own costs, which makes the two stocks a matched pair for anyone trying to gauge how much further this cycle has to run.




Leave a Reply