
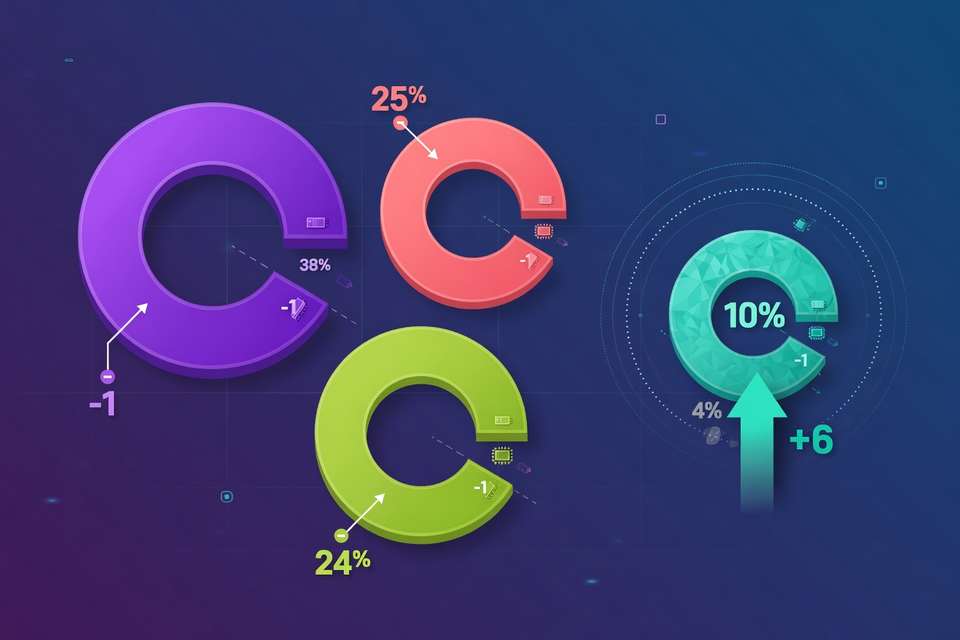
Counterpoint Research has published its second-quarter DRAM share table with Samsung at 38%, SK hynix at 25% and Micron at 24%, one point below each of the figures the firm announced in its August 4 release, and with CXMT listed at 10%, up from 4% a year earlier.
The August 4 release cited Counterpoint's Global Memory Tracker and gave Samsung 39%, SK hynix 26% and Micron 25% without putting a number on CXMT. The quarterly table cites a differently named product, the Memory Tracker and Forecast Insights Report for Q2 2026, and neither page reconciles the two sets of figures. Summed, my arithmetic, the Big Three fall from 90% on the release to 87% on the table, the difference landing on CXMT, Nanya at 2% and a 1% residual, with Counterpoint's usual rounding caveat.
Whichever set stands, the direction is the same. SK hynix has gone from 39% of DRAM revenue in Q2 2025 to 25%, and from 64% of HBM revenue to 50%, while Samsung's HBM share rose from 15% to 33% and Micron's slipped from 21% to 18%. Research Director MS Hwang said: "Although SK hynix registered record earnings sequentially and annually, it grew slower than the competition as its market share declined with Samsung and Micron squeezing from both ends."
Decoded: Counterpoint has SK hynix's quarterly revenue up 214% year over year, and it still lost 14 points of share, which tells you how fast everyone else grew. Hwang gives two reasons. SK hynix has the most HBM shipments and revenue, so falling HBM prices hit it hardest, and then there is the contract point. He said: "Second, SK hynix was earlier to sign long-term agreements (LTAs) than competitors. Long-term agreements set price ceilings and floors based on a fixed contract price, meaning fixed prices negotiated early during a period of rising memory prices would be lower than current levels." In plain terms, SK hynix ships HBM at prices fixed in a cheaper market while Samsung and Micron sell into the spike.
Counterpoint also says HBM prices fell year over year on HBM3E price drops and HBM4 delays, and that HBM4 shipments began rising in Q3 as NVIDIA Vera Rubin and AMD Instinct MI455X racks started shipping. That is the firm's claim, not a shipment count.
Micron is the one to watch on the revised table, where its gap to second place is a single point. Vice President of Research Neil Shah said: "According to our estimates, Micron’s DRAM revenue has increased fivefold since Q2 2025, positioning the company to surpass SK hynix and likely claim the second spot soon." Samsung, on the same release, was described as back at "levels last seen in 2024" after ceding the DRAM lead to SK hynix a year earlier.
CXMT was the fastest-growing supplier in the quarter on Counterpoint's numbers, up 716% year over year on domestic demand and added capacity, with Nanya up 690%. Shah said: "The question is not about ‘how’ but ‘when’ CXMT will be able to break into the Big Three Memory Club." At 10% CXMT already carries roughly two fifths of Micron's share, again my arithmetic. The revision is the detail worth keeping: Counterpoint's first cut left CXMT out of the text and its second gives it a tenth of the market. CXMT does not appear on the HBM table, which lists three suppliers.
Bootnote: The table's year-ago column has SK hynix leading DRAM at 39% with Samsung at 33%, the position the August release described as Samsung having ceded leadership. A market growing 385% year over year, Counterpoint's figure, reorders its top table quickly.


Leave a Reply