
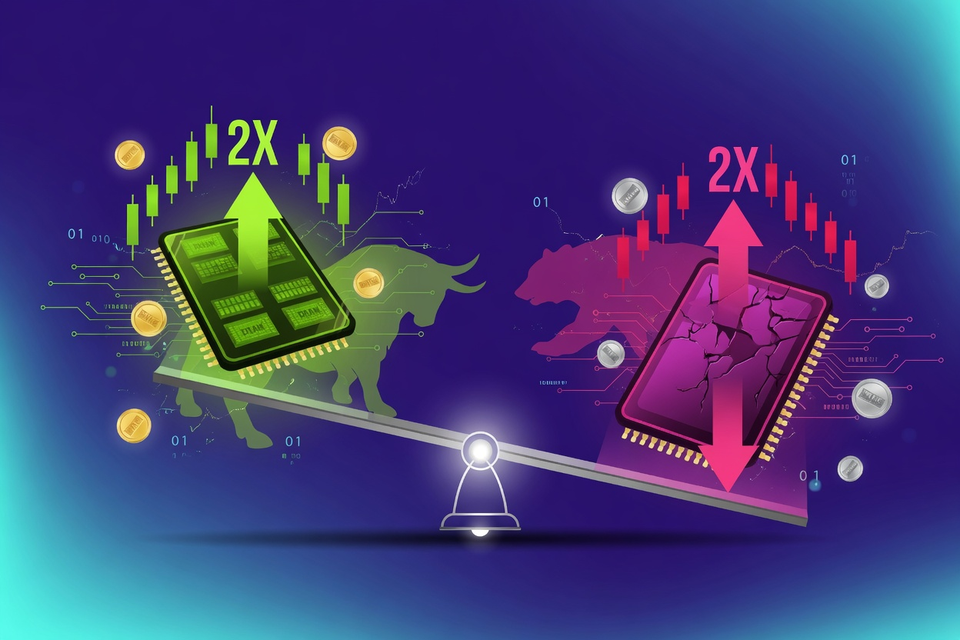
One month after handing traders a double-leveraged way to ride the memory rally, the same issuer is now selling the other side of the bet. REX Shares has scheduled its T-REX 2X Inverse DRAM Daily Target ETF, ticker RAMZ, to list on Cboe BZX on July 28, billed in the launch announcement as the first US fund of its kind.
The product seeks "daily investment results, before fees and expenses, of 200% of the inverse (or opposite) of the daily performance of DRAM," per the issuer's fund page. The DRAM in question is not a chip but the Roundhill Memory ETF, the Nasdaq-listed basket that has become the market's shorthand for the memory complex. Total expense ratio: 1.5 percent.
RAMZ arrives as the mirror of RAM, the 2x long fund the firm brought out on June 24 with a 1.25 percent fee. The pairing means both directions of the memory cycle can now be traded at double leverage off the same underlying, and the short side costs a quarter point more per year than the long.
The issuer's own risk language deserves quoting in full. "An investor could lose the full principal value of his/her investment within a single day if the price of DRAM goes up by more than 50% in one trading day," the fund page states. Translated for this tape, that is not a theoretical footnote. Memory names have been trading with violent daily ranges, and 24/7 Wall St. records the underlying ETF moving a full percent on nothing more than a Korean regulatory filing denying a merger rumor, with SK hynix swinging from a 4 percent loss to a 2 percent loss inside a session.
A second line is just as blunt: "The Fund will lose money if the underlying security performance is flat over time." Daily-reset leverage bleeds in choppy, direction-less markets, which is precisely what the memory tape has delivered between shortage headlines and profit-taking. This is a day-trading instrument, and the issuer says so, noting the fund "is designed to be utilized only by knowledgeable investors who understand the potential consequences of seeking daily inverse (-2X) investment results."
The read-through for the sector is the more interesting part. When an issuer mints paired 2x products on a memory basket five weeks apart, the DRAM cycle has stopped being a specialist fundamentals story and become a macro trading vehicle, with flows that can amplify the very swings the vendors report. The fabs set supply; the swap desks now help set the tape.
Bootnote: neither fund holds memory shares directly. Both reference the Roundhill ETF through swap agreements, which puts the actual exposure one bank contract and two wrappers away from any DRAM bit ever manufactured. Somewhere beneath RAMZ sits a fab; the paperwork between them would fill a cleanroom.
Leave a Reply