
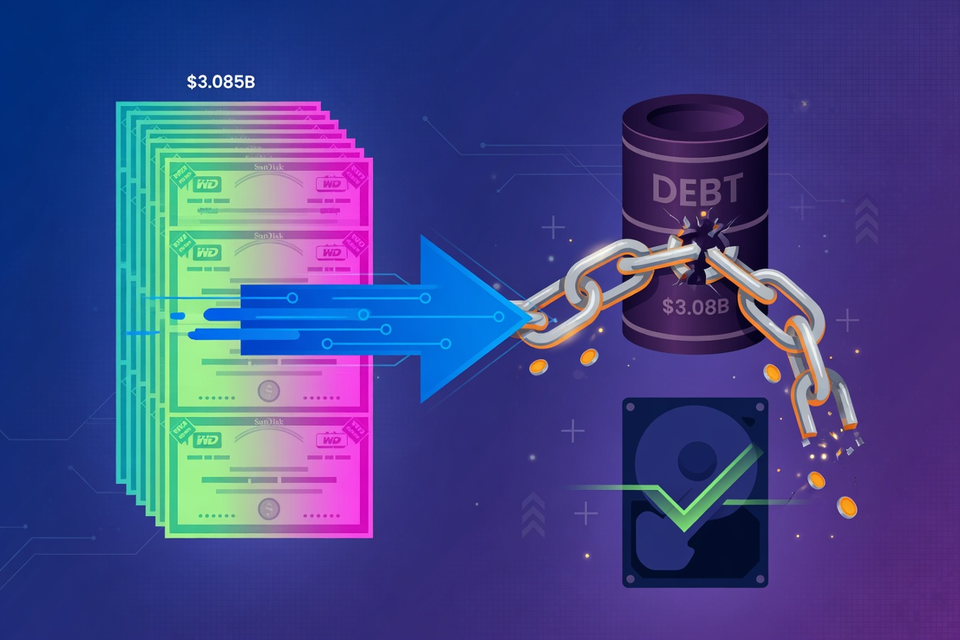
Western Digital is putting $3,085,774,648 of Sandisk common stock through the market to clear an almost identical sum of its own bank debt, and Sandisk itself gets none of the proceeds.
The mechanism is a debt-for-equity exchange rather than a straight sale. Sandisk's preliminary prospectus supplement, filed with the SEC under Rule 424(b)(7), sets out the sequence: WDC delivers the shares to affiliates of J.P. Morgan Securities LLC and BofA Securities, Inc., which currently hold the loans; those affiliates become the selling stockholders and offer the shares to the underwriters for cash. The underwriters are J.P. Morgan and BofA Securities, which is why the filing carries a section headed Underwriting (Conflicts of Interest).
Two facilities are being retired. One is the $1.586 billion of term A-3 loans and the revolving credit facility maturing in January 2027, governed by an amended and restated loan agreement dated January 7, 2022. The other is $1.500 billion of term loans maturing in March 2026, under a loan agreement dated February 5, 2026.
Add those and you get $3.086 billion, which is the offering size to within a rounding error. This deal was sized to the debt, not to a block of stock somebody wanted to move.
That March 2026 maturity is the pressure point. A $1.5 billion facility signed in February and due the following month is bridge financing, and the bridge is being repaid in Sandisk shares rather than cash.
The prospectus supplement puts it plainly: "We will not receive any of the proceeds from the sale of shares of our common stock by the selling stockholders." Translated: Sandisk's register churns, its balance sheet does not move, and the only party whose borrowings shrink is the one whose name is not on the cover.
Scale it against the float. Sandisk had 147,600,972 shares outstanding as of February 6, 2026, of which WDC held 7,513,019, or 5.1 percent. At $626.56, the closing price on February 13, 2026 and the last price the filing discloses, $3.086 billion works out at roughly 4.9 million shares, about two thirds of what WDC was holding. Both the price and the share count are left blank in the preliminary, and secondaries price below the last close often enough that the real count should land higher.
Whatever is left over is not staying put. WDC says it intends to dispose of its remaining Sandisk holding through one or more further exchanges for outstanding WDC common stock, or through pro rata distributions to WDC stockholders, or both. No timetable is given.
The rest of the register is untouched. FMR holds 13.9 percent, Vanguard 11.2 percent and BlackRock 6.0 percent, none of them selling here, and Sandisk's eleven directors and current executive officers hold 341,824 shares between them, under one percent of the company.
Bootnote: Sandisk filed an automatic shelf registration statement on the same day as the prospectus supplement, and the resale is registered under a stockholder's and registration rights agreement between Sandisk and WDC. The registration rights are the residue of the separation, which is how a former parent ends up filing paperwork through its former subsidiary to pay off its own lenders.
Leave a Reply